Market Movements, Volatility, and Trends Evaluation

Every week, we provide you with a forecast of the financial markets leading products

Based on advanced statistical models. We scrutinize the bond market, studying yields, spreads and volatility to anticipate future movements. In addition, we examine trends and volatility in the foreign exchange market, with a particular focus on the EURUSD parity, and finally, we take a look at equity indices, with a particular focus on the US S&P 500 stock index, with a brief overview of its options market.
With all these anticipations, our aim is to provide you with a more informed view of future market movements.

Update : 2026-11-16 - 2:20 am GMT
Memento
USUS Bond Market
UST yield curve

U.S. forward money-market rates rise sharply this week, with the increase concentrated mainly in intermediate maturities. The 2-year SOFR OIS rate climbs 35.5 bp to 4.731%, while the 5-year and 7-year maturities increase by 32.8 and 30.7 bp, respectively. By contrast, the 3-month rate rises by just 13.6 bp, while overnight SOFR remains relatively stable.
This divergence indicates that the market is primarily reassessing the monetary policy outlook for the coming years, without a comparable change in immediate funding conditions. The increase, particularly pronounced across the 1-year to 3-year segment, reflects an upward revision to the expected path of U.S. interest rates, with investors now pricing in higher rates or a longer period of restrictive monetary conditions. This represents a significant shift in monetary policy expectations, although it does not necessarily imply further Fed rate hikes.
SOFR futures confirm this shift. While the implied rate on the December 2026 contract rises by 16 bp, the March, June and September 2027 contracts increase by 33, 40.5 and 42.5 bp, respectively. The concentration of the move in 2027 reflects a particularly significant reassessment of the monetary policy cycle ahead. Investors appear increasingly reluctant to maintain the assumption of a relatively rapid normalization of funding conditions, a scenario that had gradually gained credibility in previous weeks. The reversal is also evident in the spread between the 2-year SOFR OIS rate and overnight SOFR, which widens from 48.6 to 83.1 bp based on the latest available observations. This move shows that the market is pricing in a substantially higher interest rate path, without a comparable change in the currently observed overnight funding rate. The question is no longer simply how long monetary policy will remain restrictive, but at what level the U.S. interest rate cycle might ultimately stabilize.

The sharp increase in forward money-market rates is accompanied by a broad rise in Treasury yields, particularly pronounced at short and intermediate maturities. The 2-year yield climbs 34.1 bp to 4.854%, compared with a 32 bp increase in the 5-year yield and a 27.9 bp rise in the 10-year yield, which closes at 5.141%. The 30-year yield rises more moderately, gaining 20.4 bp to 5.471%. This results in a flattening of the Treasury yield curve, with progressively smaller yield increases as maturities extend. The concentration of the move across the 2-year to 10-year segment confirms that the reassessment of monetary policy expectations is the main driver of higher yields, while the relative resilience of the 30-year maturity suggests a more limited adjustment in the compensation required at longer horizons. This divergence across maturities reflects a reshaping of the yield curve rather than a uniform deterioration in the valuation of U.S. government bonds.
Changes in the curve's internal structure confirm this shift in market dynamics. The 10-year versus 2-year spread narrows by 6.2 bp to 28.7 bp, while the 30-year versus 10-year spread declines from 40.5 to 33 bp. Conversely, the spread between the 2-year Treasury yield and the 3-month bill yield widens by 21.6 bp to 62.4 bp. This divergence is one of the week's most significant developments. The 2-year yield moves sharply away from the shortest money-market maturities while converging toward the 10-year yield. The short end of the curve is therefore incorporating a much faster upward reassessment of average future interest rates than the longer maturities. The 2-year/5-year/10-year and 5-year/10-year/30-year butterflies also move toward less negative levels, although their changes remain modest relative to the scale of the overall move. The rise in yields appears relatively orderly, without sufficiently pronounced internal distortions to suggest a specific dislocation at either the 5-year or 10-year maturity. Yields are rising across the curve this week, but at different rates depending on maturity, in contrast to their relatively uniform decline the previous week.
The sharp rise in Treasury yields is accompanied by a comparable increase in SOFR OIS rates, with no significant deterioration in Treasuries' relative valuation. The spread between the 2-year Treasury yield and the 2-year SOFR OIS rate narrows slightly from 13.7 to 12.3 bp, while the corresponding spreads at the 5-year and 7-year maturities decline by less than 1 bp. This stability indicates that higher Treasury yields primarily reflect the repricing of forward money-market rates rather than pressure specific to Treasuries. However, it does not provide sufficient evidence of stronger demand for U.S. government debt.

Auction results add an important qualification to the relative stability of Treasuries. The Treasury auctioned $58 billion in 3-year notes, $42 billion in 10-year notes and $25 billion in 30-year bonds, with bid-to-cover ratios declining across the three maturities. The 10-year bid-to-cover ratio fell from 2.77 to 2.46, while the 30-year ratio stood at 2.36. Indirect bidder participation also declined across all three maturities, indicating softer demand without establishing a withdrawal by foreign investors. These developments come amid a sharp rise in real yields, particularly at the 10-year maturity, which may also reflect an increase in the term premium. While the reassessment of monetary policy expectations explains a substantial part of the rise in yields, an increase in the compensation required for duration risk cannot be ruled out. The auctions therefore point to less favorable conditions for absorbing Treasury supply, although the contribution of term premiums cannot be isolated.
The repo market will face two important settlement events during the week. The first involves settlements early in the week, with $28 billion in additional net financing. The second involves three Treasury bill auctions totaling $277 billion, with settlement scheduled for the end of the week. Although these gross amounts include a substantial refinancing component, their absorption could temporarily increase dealers' liquidity needs. Against a backdrop of a sharp bond market correction, higher repo funding costs would weigh on the profitability of leveraged positions, particularly those held by hedge funds. The market's ability to absorb these settlements without renewed pressure on secured funding rates will be an important test of liquidity conditions.
For now, secured funding benchmarks show no evidence of a renewed broad deterioration in liquidity. The BGCR remains near 3.87%, while SOFR trades around 3.90% and DTCC GC repo remains slightly above both benchmarks, at approximately 3.93%. The dispersion of BGCR transactions remains narrow, and volumes are still substantial despite a slight decline over the period. The spread between DTCC GC repo and BGCR widens marginally, but the move is too small to indicate funding stress comparable to that observed in late October. At this stage, the rise in Treasury yields has not been accompanied by a comparable increase in overnight funding costs. Stable repo rates, despite the sharp rise in Treasury yields, widen gross yield differentials and improve the apparent economics of Treasury carry trades. However, this advantage remains fragile. Falling bond prices increase mark-to-market risks and margin requirements, while upcoming Treasury settlements could place additional pressure on funding costs. A rise in repo rates would then quickly erode the profitability of leveraged positions, particularly those held by hedge funds, despite higher Treasury yields.
Daily settlement fails remain broadly stable this week, with no indication of significant renewed settlement stress. These conditions will need to be reassessed following the substantial Treasury settlements scheduled for November 16 and 19, to determine whether the influx of securities creates additional collateral-related constraints.

The rise in Treasury yields is accompanied by a rebound in market-implied inflation expectations, but is driven primarily by a sharp increase in their real yield component. Inflation swap rates rise across the curve, with a particularly pronounced 11.2 bp increase in the 5-year rate to 2.386%, compared with a gain of just 2 bp at the 30-year maturity. The 5Y5Y forward remains close to 2.40%, indicating no significant renewed pressure on long-term inflation expectations. By contrast, reconstructed real yields rise by 32.9 bp at the 2-year maturity, 24.8 bp at 5 years, 23.2 bp at 10 years and 19.3 bp at 30 years. In the decomposition used, this broad increase accounts for most of the rise in nominal yields, pointing to a tightening of financial conditions driven more by the real component than by inflation expectations. It may also incorporate an increase in term premiums, although their contribution cannot be isolated. This marks a shift in the short-term market regime, with real yields and inflation compensation now rising simultaneously. Over 20 trading sessions, however, market-implied inflation expectations remain on a downward trend, while persistence and transmission indicators weaken. The market therefore appears to be reassessing the monetary policy outlook and the compensation required for bond risk rather than challenging the longer-term disinflationary trend. For the Fed, this configuration presents an important consideration, as the renewed increase in real yields could dampen economic activity and inflationary pressures by tightening financing conditions even without further monetary policy action.

The sharp rise in U.S. Treasury yields primarily reflects a reassessment of monetary policy expectations and a tightening in real yields, without a significant deterioration in Treasuries' relative valuation against SOFR OIS rates. The concentration of the move at short and intermediate maturities, combined with stable long-term inflation expectations, suggests that the market is primarily repricing monetary conditions over the coming years. However, the increase in yields is taking place in an environment still classified as "risk off", making it less convincing to attribute the correction solely to an improvement in the economic outlook. Rising risk premiums may also be contributing to upward pressure on yields, particularly through greater compensation for duration risk. Weaker auction results reinforce this concern, even as repo funding conditions remain relatively stable.
The substantial Treasury settlements scheduled for this week will test the market's ability to absorb the supply without an increase in secured funding costs. Higher repo rates would undermine leveraged carry trades and could intensify pressure on Treasuries, while stable funding conditions would limit the risk of further upward pressure on yields arising from liquidity constraints. Beyond these settlements, a more fundamental question is emerging. In an environment where real yields are rising sharply despite relatively well-anchored long-term inflation expectations, could the bond market itself tighten financial conditions enough to slow economic activity and alter the monetary policy outlook? The balance between this financial tightening, the resilience of the U.S. economy and the Treasury's financing needs will ultimately determine the extent and persistence of the current move.

To be continued...

As of today, SOFR futures and T-bills anticipate a 25 bp rate hike by the end of December 2026. This corresponds to a cumulative 50 bp increase by the end of January 2027.

US bond volatilityUS bond volatility

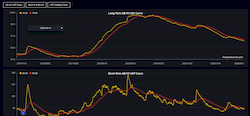
On short-term historical volatility (AB HV), US vs. Germany spreads have resumed widening following the previous week's stabilization. The movement extends across the entire curve, driven by an increase in US volatility and stable or declining German volatility. Spreads remain positive across all maturities, with no change in the relative ranking.
On long-term historical volatility (AB HV), stability remains the dominant trend. US vs. Germany spreads are unchanged across most of the curve, with a minor upward adjustment at the 2-year maturity. US volatility remains higher across all maturities, with no significant change in the overall configuration.
Compared with other European markets, short-term spreads are also widening. US volatility remains below French volatility across maturities from 5 to 30 years, while Italy retains this advantage only at the 10-year maturity, following the return of the 5-year and 30-year spreads to positive territory. Relative to the European average, spreads have turned positive across the entire curve. Over the long term, the relative ranking remains broadly stable, with US volatility higher than that of European markets, except for the Italian 10-year maturity, which is now at parity.

Volatility (AB HV) Trend Historical level Risk of violent variation Move Index (IV) HV - Move Index (IV)
Long-term Medium Medium
Short-term Standard
Volatilité des Treasuries US

Long-term historical volatility (AB HV) continues to show little change, with a limited adjustment of +10 bp at the 2-year maturity and stability across the other maturities. In contrast, short-term vs. long-term HV spreads have resumed widening across the entire curve, by +30 to +40 bp. They remain positive, ranging from +40 to +160 bp. This movement reverses the narrowing observed the previous week across maturities from 5 to 30-year, while widening continues at the 2-year maturity. The movement remains primarily driven by recent volatility, with no significant change in the long-term historical volatility regime.
Short-term HV increases by +40 bp across maturities from 2 to 10-year and by +30 bp at the 30-year maturity. Unlike the previous week, the increase now extends across the entire curve. Its downward-sloping profile nevertheless remains unchanged, with volatility still peaking at the 2-year maturity, 20 bp above the 5-year maturity. This relatively uniform increase confirms that historical volatility (HV) remains concentrated at the shorter maturities, with no further significant shift.

Following the previous week's decline, the MOVE IV rebounds by 6.02 points to 98.79, while the MOVE AB HV increases more moderately by 3.94 points to 86.91. The divergence between the two indicators therefore resumes, mainly driven by the rise in implied volatility. The simultaneous increase in HV also confirms a rise in realized market fluctuations, although these moderate toward the end of the week.
Our IV vs. HV spread widens from 9.80 to 11.88 points (+2.08), partially reversing the previous narrowing. This movement reflects a relative increase in the implied volatility premium, making the options protection represented by the MOVE relatively more expensive compared with realized volatility. Nevertheless, the spread remains below its level of two weeks earlier, without prejudging hedging conditions across the entire UST options market.

European UnionEuropean bond market
European curve yield

After several weeks of declining yields, European sovereign bond yields have risen sharply again, driven by a repricing of monetary policy expectations affecting all issuers. This broad-based move masks growing differences in their relative valuations. France, which had benefited from the most favorable yield correction the previous week, has lost that advantage and is once again underperforming its peers, particularly at intermediate and long maturities. Italy, by contrast, is proving considerably more resilient to the general rise in yields, while Spain maintains a relatively steady trajectory. Germany is closely tracking the monetary repricing, without experiencing the deterioration seen in certain segments of the French curve. The key development is therefore not simply the end of the decline in yields, but the reversal in the relative performance of European sovereign bonds that has accompanied it.

The rise in yields is concentrated primarily in the 2-year to 10-year maturities, while 30-year yields have generally recorded smaller increases. This has flattened the long end of all four curves, although their intermediate segments have behaved differently. In Germany, the 2-year Bund yield rises by 15.3 bp, compared with 14.3 bp at the 5-year maturity and 13.3 bp at the 10-year maturity, bringing the latter to 3.378%. The 2-year to 10-year slope consequently narrows by 2 bp to 24.4 bp. This relatively uniform movement reflects a broadly consistent transmission of monetary repricing, without any significant change in the shape of the intermediate curve. The 30-year yield increases by a more moderate 10.7 bp, reducing the 10-year to 30-year slope to 36.2 bp. The German bond market has therefore returned to a configuration in which expectations for interest rates over the coming years play a greater role in weekly yield movements than the additional compensation required for very long-term commitments.

France stands out for a more pronounced increase in yields beyond the 2-year maturity. The 5-year OAT yield rises by 16 bp to 4.340%, while the 10-year gains 16.2 bp to 4.921% and the 30-year increases by 15.4 bp to 5.463%. At the 2-year maturity, the increase is limited to 13.2 bp. This pattern produces a renewed 3 bp steepening of the 2-year to 10-year curve, bringing its slope to 129.3 bp and reversing the slight flattening recorded the previous week. Most of this change occurs in the 2-year to 5-year segment, where the slope widens by 2.8 bp, while the 5-year vs. 10-year segment remains virtually unchanged. The French yield curve is therefore not experiencing a uniform upward shift. Intermediate maturities are absorbing a greater share of the repricing, while longer maturities continue to carry elevated yields. Despite a slight flattening between 10 and 30 years, the long-end slope remains at 54.2 bp, well above that of the Bund curve. The previous week's correction has therefore failed to produce a lasting change in the shape of the French curve. It now appears more consistent with a temporary narrowing of previously accumulated spreads than with the confirmed beginning of a normalization in French sovereign valuations.

Italy shows a markedly different pattern, confirming its improving relative performance against other European sovereign issuers. The 2-year BTP yield rises by just 3 bp to 3.491%, while the 5-year increases by 11.3 bp and the 10-year by 8.2 bp to 4.419%. Following the exceptional 19.1 bp flattening of the 2-year to 10-year curve recorded the previous week, the slope steepens slightly by 5.2 bp to 92.8 bp. However, this does not reflect a uniform increase in yields across maturities. The 2-year to 5-year segment steepens by 8.3 bp, while the 5-year to 10-year segment flattens by 3.1 bp. The belly of the Italian curve is therefore undergoing another redistribution of yields without reversing most of the previous week's structural adjustment. More importantly, the limited 5.7 bp increase in the 30-year yield, to 4.997%, confirms the relative resilience of long-dated Italian debt. Italy is no longer benefiting from falling yields, but it is managing to contain their increase, resulting in a genuine improvement in its relative valuation in a less supportive monetary environment.

Spain maintains a more stable curve structure, with a fairly uniform increase in yields between the 2-year and 10-year maturities. The 2-year Bonos yield rises by 12.3 bp to 3.185%, compared with 12.5 bp at the 5-year maturity and 10.9 bp at the 10-year maturity, bringing the latter to 3.939%. The 2-year to 10-year slope narrows slightly to 75.4 bp, while the 10-year to 30-year slope declines to 51.3 bp. This configuration reflects considerable sensitivity to the shift in monetary policy expectations, without any significant distortion of the curve. Unlike Italy, which stands out for the resilience of its short- and long-dated yields, Spain is more closely following the general rise in European benchmark rates. Nevertheless, it continues to improve its position modestly relative to Germany, particularly at the 10-year maturity. Spanish sovereign debt therefore retains a relatively favorable valuation, without displaying country-specific pressures that would materially alter the broader assessment of its bond market.

The €STR OIS curve provides important insight into the drivers of this reversal. Following the substantial correction of the previous week, synthetic money market rates have rebounded sharply, with the increase concentrated mainly in maturities between 1 and 4 years. The 2-year OIS rate rises by 14.6 bp to 3.066%, while the 3-year gains 14.9 bp and the 4-year increases by 14.5 bp. The rise then moderates to 11.1 bp at the 5-year maturity and 8.6 bp at the 6-year maturity. By contrast, the 3-month rate increases by only 4.3 bp, while the spot €STR rate remains stable. This divergence shows that the market is primarily repricing the monetary policy outlook for the coming years rather than immediate funding conditions. The previous easing in rate expectations has therefore been partly reversed, although this does not automatically imply any particular future ECB decision. The quarterly structures of €STR and Euribor futures reinforce this interpretation, with implied rates continuing to rise between late 2026 and the first expiries of 2027, before their upward progression slows significantly. The market now expects the ECB to keep interest rates elevated for longer, even though its policy rates have not yet changed.
Comparing sovereign yields with OIS rates nevertheless shows that not all issuers are affected to the same extent. At the 2-year maturity, the Bund yield rises almost in line with the monetary benchmark, with its sovereign vs. OIS spread widening by just 0.7 bp. France even benefits from a slight 1.4 bp tightening, while Italy records a much larger 11.6 bp compression. This latter move explains why the 2-year BTP yield has been particularly resilient to the general increase in rates. At the 5-year maturity, however, the picture becomes less favorable for France. The OAT vs. OIS spread widens by 4.9 bp, compared with 3.2 bp for the Bund, while the BTP spread remains virtually unchanged. The increase in French yields is therefore no longer driven solely by the rise in common monetary benchmarks. It also reflects an increase in the relative compensation required at intermediate maturities, while Italy remains better positioned to absorb this repricing.
This difference becomes particularly evident at the 10-year maturity, although the construction of the synthetic OIS curve requires an important distinction. The 10-year €STR OIS rate rises by only 3.4 bp to 3.195%, compared with a 16.2 bp increase in the OAT yield. The French spread over OIS consequently widens by 12.8 bp to 172.6 bp. However, unlike the shorter maturities derived from futures, the synthetic 10-year OIS benchmark is partly constructed using Bund yields. Its movement therefore does not provide a fully independent measure of German sovereign market conditions. The extent of the widening in the OAT vs. OIS spread must be interpreted with this limitation in mind, without diminishing the significance of the observed move. Relative to the Bund, whose yields can be compared directly, the French spread also widens, although more moderately. Comparing the two benchmarks therefore confirms a deterioration in the relative valuation of OATs, while showing that its magnitude depends significantly on the instrument used to measure the common monetary benchmark.

The relative ranking of European sovereign issuers has now shifted in the opposite direction from the previous week. The 10-year OAT vs. Bund spread widens by 2.9 bp to 154.3 bp, while the BTP vs. Bund spread narrows by 5.1 bp to 104.1 bp. Spain also improves its relative position, with its spread over Bunds tightening by 2.4 bp to 56.1 bp. France is therefore the only one of the three issuers to record a deterioration relative to Germany at this maturity. The divergence becomes more significant when compared with Italy.
Following the previous tightening, the 10-year OAT vs. BTP spread widens by 8 bp to 50.2 bp. At the 30-year maturity, the widening reaches 9.7 bp, bringing the spread to 46.6 bp. The deterioration in French relative valuations also extends to intermediate maturities, with the 5-year OAT vs. BTP spread increasing by 4.7 bp. Even at the 2-year maturity, where France slightly improves its position relative to Germany, it loses 10.2 bp against Italy, whose yields rise much more slowly. France is therefore experiencing more than a general increase in interest rates. Its relative valuation is deteriorating once again against sovereign issuers that are now better able to contain this upward pressure.

The 30-year maturities reinforce this distinction. The OAT vs. Bund spread reaches 172.3 bp, widening by 4.7 bp, while the BTP vs. Bund and Bonos vs. Bund spreads narrow by 5 bp and 1 bp, respectively. France also remains at a disadvantage relative to Spain, with a yield differential exceeding 100 bp at this maturity. These developments show that the general rise in rates is not accompanied by a uniform repricing of the premiums associated with long-dated sovereign debt. The resilience of the 30-year BTP contrasts with the almost equal increases in French 10-year and 30-year yields. For France, the issue is no longer limited to the persistence of a historically steep curve. It also concerns the ability of its long-dated debt to maintain its relative valuation when monetary policy expectations become less favorable. Future funding requirements, bond supply, the political instability caused by E. Macron, fiscal constraints and the compensation required to commit capital over several decades are all potential factors behind this divergence.

The 10-year interest rate swaps (IRS) confirm this hierarchy of valuations. The euro swap rate trades around 3.42%, slightly above the German Bund yield, while remaining well below French and Italian sovereign yields. The spread between the IRS rate and the French OAT yield is approximately −150 bp, compared with nearly −100 bp for the BTP and −52 bp for Spanish Bonos. This configuration highlights the persistently elevated yield required on French sovereign debt relative to the euro swap market, while German debt remains close to that benchmark. The magnitude of these spreads further confirms that OAT valuations remain far removed from common financial benchmarks, beyond differences in monetary policy expectations alone.

Inflation swaps and synthetic real yields provide a further distinction. Over the past twenty trading sessions, the French 10-year nominal yield has increased by 12 bp, while inflation expectations derived from swaps have declined by 7.9 bp. The synthetic real yield component has consequently risen by 19.9 bp. In Germany, the nominal yield has fallen by 6.2 bp over the same period, mainly reflecting lower inflation expectations, while the real component has remained almost unchanged. In Italy, the decline in inflation swaps has offset a more limited increase in synthetic real yields. These movements extend beyond the latest week's changes, but they show that the French repricing is part of a longer-standing trend toward higher nominal compensation excluding expected inflation. At the 10-year maturity, the French synthetic real yield stands at 2.917%, compared with 2.465% in Italy, while their respective inflation swap rates remain relatively close at 2.004% and 1.954%. Most of the nominal yield differential between France and Italy at this maturity therefore remains embedded in the residual real component, which also incorporates other financial premiums and does not represent a pure measure of the risk-free real yield.
At very long maturities, this decomposition changes. The French 30-year inflation swap rate stands at 2.408%, or 40.4 bp above the 10-year rate, while the equivalent Italian slope is limited to 13 bp. At the 30-year maturity, the spread between French and Italian inflation swaps reaches 32.4 bp, compared with 46.6 bp for the OAT vs. BTP yield spread. This difference accounts for a substantial share of the nominal yield differential, with the remainder reflected in synthetic real yields. This particular feature suggests that the compensation required on very long-dated French debt is not driven by the same components as at intermediate maturities. The persistence of higher inflation expectations over distant horizons contributes to maintaining a steep nominal yield curve, without explaining its weekly movement on its own. Nor does it imply that actual inflation is accelerating. The market is distinguishing between the long-term inflation outlook, real yield compensation and the various premiums required to hold sovereign debt.

An examination of financial risk indicators adds nuance to the deterioration in French sovereign valuations. Our national risk indicator falls from 1.902 to 1.733, but remains significantly above Germany's reading of 0.212 and Italy's 0.125. Despite this improvement, France remains in a Risk Off regime, while its sovereign spreads widen relative to both countries. This divergence confirms that the easing in financial risk has not been accompanied by an improvement in the relative valuation of OATs.
One development in the French market warrants particular attention. The deterioration in OAT relative valuations is heavily concentrated in the final trading session of the week. On November 12, the 10-year OAT vs. Bund spread had narrowed to 147.8 bp, compared with 151.4 bp the previous Friday. On November 13, it widened sharply to 154.3 bp, an increase of 6.5 bp in a single session. This move is not confined to the 10-year maturity. The French-German yield differential also widens by 4.7 bp at the 5-year maturity and 5.4 bp at the 30-year maturity during the final session. More significantly for short-term funding conditions, the spread between French and German 3-month sovereign yields increases from 22.9 to 29.7 bp. This simultaneous deterioration across short, intermediate and long maturities points to a repricing specific to French sovereign debt rather than simply an extension of the broader rise in European monetary rates. Its concentration at the end of the week warrants monitoring, although the size of the move does not yet support the conclusion that market functioning has been disrupted.
The deterioration in OAT valuations has not yet translated into significant stress in bank funding or secured financing. By the end of the week, the French repo rate rises from 2.529% to 2.545%, compared with an increase from 2.504% to 2.514% in Germany, widening the French-German differential from 2.5 to 3.1 bp, still below the 5.5 bp monitoring threshold. French repo rates also remain close to those of Italy and Spain. However, the spread between 3-month Euribor and the French 3-month sovereign yield deteriorates from −0.6 to −8.6 bp, indicating an increase in the relative yield required on short-term French government debt. This contrasts with the narrowing of the Euribor vs. OIS spread from 22.9 to 16.6 bp, which does not indicate any generalized increase in bank funding stress. The OAT vs. Bund spread nevertheless remains above the 99th percentile of its historical distribution, while the monitoring framework has triggered only its first-level sovereign risk alert.

The key question now is whether French sovereign market pressures will spill over into funding conditions. The latest banking and repo observations predate the sharp deterioration in OAT valuations on November 13. A sustained increase in the FRA vs. GER repo spread, accompanied by wider differentials against Italy and Spain or rising bank funding spreads, would signal that pressures are spreading beyond the government bond market. Conversely, stable secured funding conditions together with tighter OAT vs. Bund and OAT vs. BTP spreads would confirm that the deterioration remains primarily confined to sovereign valuations. The European bond market is therefore not signaling a French funding crisis, but persistently elevated OAT premiums and their potential transmission to the financial system now represent a major risk to monitor.

As of today, Euribor and €STR futures anticipate a 25 bp rate hike by the end of December 2026. This corresponds to a cumulative increase of approximately 36 bp by the end of January 2027.

You will find details of the various components of European bonds below and more in the Interest Rates section.

EU bond volatilityEuropean bond volatility
Volatilité des Treasuries US

Long-term HV for the EU aggregate remains virtually stable, with a minor adjustment of +3 bp at the 10-year maturity. The inertia observed in previous weeks continues. Germany remains the least volatile across all maturities, with no change. France is unchanged, while Italy records a 10 bp increase at the 10-year maturity. France and Italy remain at parity at the 2-year maturity, while Italy maintains higher levels from 5 to 30-year.

  • GER — Short-term HV declines by 30 bp at the 2-year maturity, remains stable at 5 year and falls by 10 bp at longer maturities. Germany continues to exhibit the lowest volatility levels. Short-term vs. long-term HV spreads narrow, except at the 5-year maturity, and reach zero at 10-year.
  • FRA — Short-term HV continues to decline across maturities from 2 to 10-year (−20 to −50 bp), while remaining stable at 30 years. It remains higher than Italy's from 5 to 30-year, but lower at 2 years. Spreads remain positive and narrow, except at the 30-year maturity.
  • ITA — Short-term HV increases slightly at the 2-year maturity (+10 bp), unlike the other sovereign markets, but declines elsewhere (−10 to −20 bp). Spreads remain positive, widen at 2-year and narrow across the other maturities, despite the increase in long-term HV at the 10-year maturity.
European union flagEUR and USD crosses

USA flag The US dollar is strengthening against a significantly broader range of currencies, marking a shift from the previous week, when its firmness was primarily driven by corrections in currencies exposed to the global economic cycle and commodities. The main change now stems from a particularly pronounced rise in US interest rate expectations, supported by the resilience of the domestic economy, persistent inflationary pressures and hawkish communications from the Federal Reserve. The rebound in sovereign yields reinforces the dollar's yield advantage and encourages investment allocations in its favor. This trend continues to be accompanied by significant differentiation among currencies, with some emerging market and Asian currencies showing renewed resilience. The reversal in the Swiss franc nevertheless suggests that interest rate differentials are regaining importance relative to safe-haven considerations. Historical volatility is evolving unevenly across markets, without indicating widespread disruption in foreign exchange markets. The dollar's appreciation therefore reflects a strengthening of its monetary attractiveness rather than a broad-based search for liquidity.

  • In Europe, the reversal in the Swiss franc represents the most significant development. After benefiting from persistent safe-haven demand, the Swiss currency has depreciated markedly, as rising US yields reduce the relative attractiveness of its low remuneration, highlighting the renewed importance of interest rate differentials. The Swedish krona is also extending its decline despite the Riksbank's monetary tightening. Sterling is losing further ground despite the Bank of England's recent tightening. Concerns over energy costs and their impact on British consumption are limiting the support provided by domestic interest rates. The Polish zloty and Hungarian forint are both reversing their previous appreciation, as higher US yields weigh on the relative attractiveness of investments denominated in these currencies. The Norwegian krone continues to depreciate, although at a slower pace than the previous week, when falling oil prices had reduced its appeal. Renewed tensions in the Middle East, particularly threats to Saudi energy infrastructure, could alter this environment.
  • In Asia, the South Korean won is staging a marked recovery following its sharp depreciation, despite persistent uncertainty surrounding artificial intelligence investment and Nvidia's corporate governance. This rebound is supported in particular by exporters converting foreign currency revenues and foreign investors purchasing Korean equities, despite continuing uncertainty over the outlook for the technology sector. The Malaysian ringgit is also extending its depreciation despite the resilience of domestic industrial activity. Rising US interest rate expectations are reducing its relative attractiveness.
    Against the yen, the dollar is extending its appreciation, now supported by a substantially more hawkish repricing of US monetary policy expectations. The rise in US forward interest rates, particularly pronounced at short and intermediate maturities, exceeds that observed in Japanese rates, where adjustments are more concentrated at longer maturities. The widening of yield differentials reinforces the attractiveness of yen-funded carry strategies, despite the expected continuation of monetary normalization in Japan. Yen weakness nevertheless complicates the Bank of Japan's policy trade-offs by increasing the cost of energy imports, potentially fueling inflation while weakening consumption.
    USDJPY funding conditions have improved slightly following a temporary deterioration, with the funding basis becoming less negative, although distortions persist at certain intermediate maturities. These irregularities reflect differentiated adjustments across funding markets without indicating a generalized dollar shortage. The increase in cleared outstanding positions in Japanese interest rate swaps confirms a reconfiguration of monetary positions, without making it possible to identify directional flows in the foreign exchange market. Unlike the previous week, the dollar's appreciation is therefore driven more by the tightening of US monetary policy expectations than by weakness in the Japanese monetary outlook alone. The risk of intervention by Japanese authorities, whose deterrent effect could be weakened by limited US participation, nevertheless increases the sensitivity of carry positions to changes in interest rate expectations.
  • In the Americas, the Canadian dollar continues to depreciate, as persistent weakness in the Canadian labor market weighs on the economic outlook and limits the support provided by recent monetary tightening, while uncertainty surrounding oil prices complicates expectations for energy revenues. Conversely, the Mexican peso is maintaining its appreciation despite the firmness of the US dollar. The upside inflation surprise reinforces expectations of a pause following Banxico's recent rate cut, preserving the attractiveness of domestic investments and supporting the view that the previous easing was a one-off adjustment. The Brazilian real is extending its depreciation, confirming persistent fiscal concerns following Lula's reelection. Rising inflation expectations, despite recent data coming in slightly better than expected, and a deteriorating growth outlook are complicating the central bank's policy trade-offs. The Chilean peso is also reversing its previous appreciation, weighed down by declining copper prices and concerns over Chinese industrial demand.
  • In Oceania, the Australian dollar continues to depreciate, although at a slower pace than the previous week. Persistent weakness in China's property sector continues to weigh on the outlook for industrial commodity exports, particularly iron ore, while Australia's monetary policy outlook remains restrictive without being sufficient to offset economic concerns. The New Zealand dollar, by contrast, has largely halted its correction, despite weak consumption, a fragile labor market and an uncertain growth outlook.
  • In Africa, the South African rand is experiencing particularly pronounced depreciation, accompanied by an increase in its historical volatility. Political uncertainty following municipal elections continues to raise questions about the stability of future governing coalitions. Investors are also monitoring upcoming inflation data and central bank decisions, in an environment where potentially higher energy costs complicate the monetary outlook. The Egyptian pound, by contrast, continues to recover, although at a substantially slower pace following its exceptional appreciation. Improved foreign currency availability, renewed external financing and the rebuilding of reserves are helping to ease immediate concerns over liquidity requirements, without eliminating structural vulnerabilities.
  • In the Middle East, the Israeli shekel continues to depreciate, as political uncertainty and regional geopolitical tensions sustain a risk premium on Israeli assets. The significant easing of its historical volatility nevertheless reflects a moderation in fluctuations following earlier turbulence, without confirming a lasting improvement in investor confidence.

The dollar's historical volatility maintains a downward long-term trajectory and is now approaching some of the lowest levels observed over the period. In the short term, the recovery following recent lows is losing momentum and giving way to stabilization, without any renewed acceleration in fluctuations. Weekly data nevertheless reveal significant divergences, with volatility increasing against certain emerging market and Oceanian currencies, offset by easing across several other markets. Despite the dollar's more widespread appreciation, overall volatility remains relatively contained, and pressure indicators do not signal persistent stress. This divergence between directional strengthening and the intensity of fluctuations suggests that foreign exchange adjustments are still taking place without a generalized change in the historical volatility (HV) regime.


Drapeau EU The euro is experiencing relatively widespread depreciation, reversing the recovery observed the previous week. Its weakness is particularly pronounced against Asian currencies and several emerging market currencies, while its gains remain concentrated against certain European currencies and economies facing specific domestic vulnerabilities. The rise in European interest rate expectations, particularly noticeable at intermediate maturities, is insufficient to preserve its relative attractiveness. Renewed energy tensions are complicating the ECB's outlook by sustaining imported inflation risks while growth and industrial competitiveness remain constrained. Differences in fiscal headroom among member states also constitute a source of vulnerability in the event of additional economic support requirements. Unlike the previous week, corrections in currencies exposed to the global economic cycle are no longer providing as much support for the euro. The reversal in the Swiss franc represents a notable exception but does not alter the assessment of broad-based weakness in the single currency.

  • In Europe, the Swiss franc is experiencing a particularly pronounced downward reversal, as rising European interest rate expectations reduce the relative attractiveness of its low remuneration, while moderate Swiss inflation limits the prospects for monetary tightening by the Swiss National Bank. The Swedish krona also continues to weaken despite the Riksbank's recent rate increase. Uncertainty surrounding energy costs appears to be reducing the relative support provided by Swedish monetary policy, although the recovery in domestic activity remains a source of resilience. The Hungarian forint and Polish zloty are both surrendering part of their previous gains. Hungary's continued cautious monetary policy stance is not sufficient to fully preserve the forint's advantage, while Poland's fiscal financing requirements continue to raise concerns about the outlook for public funding. The Czech koruna is also undergoing an adjustment despite recent tightening by its central bank, as energy-related inflation risks and uncertainty over demand from German industry limit its relative attractiveness. The Romanian leu continues its gradual depreciation within a relatively managed exchange rate framework, with fiscal consolidation difficulties, the external deficit and dependence on European funding sustaining concerns over financial stability. The Norwegian krone, by contrast, has halted its sharp correction. Renewed tensions surrounding Middle Eastern oil infrastructure are altering energy expectations following the decline in prices that had weighed on the currency, without establishing a lasting improvement in its outlook.
  • In the Americas, the Mexican peso is extending its appreciation against the euro, confirming its resilience following the previous monetary easing. The upside inflation surprise and emerging disagreements within Banxico are raising questions about the appropriateness of further rate cuts, while the announcement of a prolonged period of monetary stability is helping to preserve the domestic yield advantage. This movement confirms that the recent rate reduction has not triggered the immediate deterioration in the peso's attractiveness that investors might have feared, without eliminating the risks associated with persistent inflation. The Brazilian real is extending its depreciation against the euro, as fiscal concerns continue to outweigh the advantage provided by high domestic interest rates. Despite recent inflation coming in slightly below expectations, medium-term inflation expectations remain far from the central bank's target, while slowing growth complicates the prospects for further monetary tightening. The Chilean peso is also reversing its previous appreciation, weighed down by the continued decline in copper prices. The Argentine peso, by contrast, is regaining an advantage against the euro following its previous depreciation. Moderation in core inflation represents an encouraging development for the stabilization process, although headline inflation continues to be affected by adjustments to administered prices. This relative improvement does not, however, establish a lasting normalization of Argentina's monetary and financial conditions.
  • In Asia, the South Korean won is staging a particularly strong recovery following its sharp depreciation. Despite persistent uncertainty surrounding investment in artificial intelligence, the rebound in Korean technology stocks and the conversion of export revenues appear to have helped ease pressure on the currency. This reversal nevertheless reflects a position adjustment more than a confirmed improvement in the sector's outlook. The Taiwan dollar is also regaining an advantage against the euro, as resilient electronics exports and demand for strategic components support the industrial outlook, despite concerns over the financing of digital investment. The Indian rupee is extending its relative appreciation, benefiting from the recent return of foreign investment to domestic equities. However, rising oil prices and a widening trade deficit are limiting this support, while renewed inflationary pressures complicate the monetary policy outlook. The Indonesian rupiah is also extending its appreciation against the euro despite political uncertainty surrounding the vice president's resignation. The relatively contained reaction of local bond markets suggests that investors do not anticipate an immediate challenge to monetary stability. Nevertheless, the risk of capital outflows linked to equity index adjustments and external financing requirements remains a source of vulnerability. The Singapore dollar is also reversing its previous weakness, supported by a monetary policy framework based on the gradual appreciation of the effective exchange rate to contain imported inflation. The Turkish lira is also regaining an advantage against the euro despite the central bank's upward revision of its inflation forecasts.
    Against the yen, the euro has halted its appreciation and recorded a slight correction following several weeks of gains. Unlike the previous week, Japanese interest rate expectations are rising, primarily at intermediate and longer maturities, reflecting a reassessment of the Bank of Japan's monetary normalization timetable. European forward rates are also rising at short and intermediate maturities, preserving the euro's yield advantage without being sufficient to sustain its appreciation. The movement therefore appears to reflect a readjustment of positions rather than a deterioration in European interest rate differentials, while easing historical volatility suggests stabilization rather than a confirmed trend reversal.
    EURJPY funding conditions improved towards the end of the week following a temporary deterioration, although significant irregularities persist across the term structure, without indicating widespread liquidity stress. The increase in cleared outstanding positions in Japanese interest rate swaps confirms a reconfiguration of monetary positions, without allowing directional foreign exchange flows to be inferred. Uncertainty surrounding the pace of Japanese monetary tightening, European economic vulnerabilities and the risk of intervention by Japanese authorities remain the main factors affecting carry strategies. Their attractiveness continues to be supported by yield differentials, but they have become more exposed to adjustments in monetary policy expectations.
  • In Oceania, the New Zealand dollar is staging a marked appreciation against the euro following its sharp depreciation. This recovery is taking place despite still-fragile domestic demand and an uncertain economic outlook. The resilience of domestic bond investments and the fading of the previous correction are helping to explain this relative improvement, without demonstrating a lasting strengthening of economic fundamentals.
  • In Africa, the euro is extending its appreciation against the South African rand, which is being weighed down by political uncertainty following municipal elections. Fragmentation within local councils and negotiations between political parties are raising questions about coalition stability and the continuity of economic reforms, while tighter international financial conditions are reducing the relative attractiveness of South African assets. The Egyptian pound, by contrast, continues its recovery following the particularly strong appreciation recorded the previous week. Renewed external financing and improved foreign currency availability are helping to alleviate immediate concerns over refinancing requirements. This improvement nevertheless remains dependent on continued international funding and does not eliminate the structural imbalances of the Egyptian economy.

The euro's historical volatility continues to show a structural slowdown, although the easing observed over recent months now appears to be entering a consolidation phase. In the short term, fluctuations remain uneven, with episodes of stress quickly followed by periods of easing, without the establishment of a sustained upward trend. The recent decline in pressure indicators points to fading market nervousness despite the relatively widespread depreciation of the single currency.

Europe flagEURUSD Pair

The EURUSD's 120-pip decline primarily marks the end, at least temporarily, of the divergence between a weakening spot exchange rate and monetary convergence that had remained favorable to the euro. Following the partial correction of the previous week, the dollar's interest rate advantage is rebuilding across the entire curve, driven by a much sharper rise in US interest rates than in their European counterparts. This repricing calls into question the relative support the euro had continued to enjoy and provides a more coherent monetary backdrop for its depreciation. Short-dated forwards fully reflect the decline in the spot rate, while rising forward points eventually push longer-dated maturities higher, without implying expectations of an appreciation of the European currency.
Changes in spreads between US money market rates, considered alongside indicators of international dollar funding conditions, do not yet reveal sufficiently consistent signs of stress to support the hypothesis that a dollar liquidity shortage is driving the euro's decline. The move appears to reflect a rebuilding of the dollar's yield advantage rather than demand for the US currency driven by funding constraints. This distinction matters, as the EURUSD's weakness now has a more coherent monetary foundation, without funding conditions indicating widespread pressure on liquidity. A continuation of this repricing could therefore prolong the euro's vulnerability, without a generalized tightening of dollar funding conditions being necessary to explain its depreciation..

The 30-day implied volatility (IV) of EURUSD edges higher, but fails to sustain the recent upward spikes. This modest increase marks a shift from the stabilization observed the previous week, although attempts to move higher continue to fade quickly, keeping volatility expectations at relatively low levels.
The options market thus appears to be incorporating greater nervousness without a sustained reassessment of the magnitude of future exchange rate fluctuations, despite the euro's persistent weakness. Meanwhile, short-term historical volatility is recovering and has moved slightly above its long-term benchmark, indicating an intensification of realized fluctuations that IV only partially reflects. The volatility regime remains subdued, but its recent stabilization is becoming more fragile, leaving room for occasional spikes rather than a confirmed reversal.

WorldEquity Indices

EQUITY INDICES — USA

The rebound in US equity indices this week does not fundamentally change our assessment of the correction that began earlier. The rise in nominal and real interest rates, which triggered the initial selling pressure in technology stocks, remains the main constraint on equity markets. This comes as artificial intelligence plays an increasingly important role in investment spending, earnings expectations and the performance of major indices. The market therefore faces a contradiction, as the growth expectations supporting valuations depend on massive investment commitments that are becoming more expensive to finance as monetary conditions tighten. The rebound demonstrates investors' continued interest in this technology cycle without resolving that contradiction. It also suggests greater selectivity, with the future profitability of investments taking precedence over their expansion alone.
Recent developments could exacerbate this instability. The political consequences of the midterm elections are introducing uncertainty over the pace of digital infrastructure development. Meanwhile, despite the recent easing of tensions in the repo market, this week's liquidity drain could put pressure on US equity markets. If accompanied by renewed funding constraints, it could trigger forced selling and amplify equity market volatility. The inflation outlook also offers little support for a rapid easing of monetary policy. With US refineries operating at particularly high utilization rates, their ability to absorb another supply shock is limited, sustaining the risk of further upward pressure on refined petroleum product prices. Adding to these concerns is uncertainty surrounding Nvidia, where further developments could trigger additional market volatility. Together, these factors represent potential catalysts for another correction, without necessarily undermining the long-term development of artificial intelligence.
The fundamental issue facing US equity markets remains the impact of persistently high real interest rates, or even further monetary tightening, on economic growth. The risk is a gradual weakening of consumption, investment and corporate earnings. Lower interest rates could support equity indices if they accompanied disinflation without a major economic slowdown. Conversely, if rates declined in response to a sharp deterioration in economic activity, falling earnings could offset the positive impact of lower rates on valuations. The central question is therefore how much artificial intelligence and its related industries are actually contributing to US economic growth compared with the rest of the economy. The challenge is to determine how far this investment engine can continue supporting economic activity and equity markets while other sectors face the effects of restrictive monetary conditions. Ultimately, will high interest rates kill the goose that lays the golden eggs?

EQUITY INDICES — EUROPE

The resilience of European equity indices this week, with some reaching new highs, contrasts with the persistent difficulties facing U.S. markets. This divergence reflects their sector composition, which is less dependent on large-cap technology stocks and more diversified across industry, finance, healthcare, and consumer sectors. Corporate earnings releases have also provided meaningful support, although the significant contribution from the energy sector calls for a more cautious interpretation of this earnings improvement. Part of the advance in European equities has benefited from international portfolio reallocations away from U.S. stocks most exposed to artificial intelligence. These capital flows provide support for European indices but do not reflect a corresponding improvement in Europe's economic outlook. It is therefore important to distinguish a relative revaluation of European equities from a genuine acceleration in their earnings growth.
This distinction is particularly important in an environment where European companies remain highly exposed to global economic conditions. Weak domestic demand in China, uncertainty surrounding U.S. technology investment, and persistent energy tensions could simultaneously weigh on the outlook for industrial and export-oriented companies. The energy shock has contrasting effects on European equity indices. While higher oil prices may support producers' earnings, rising costs of refined petroleum products and, above all, natural gas, on which European industry remains heavily dependent, weigh on production costs, corporate competitiveness, and household purchasing power, undermining prospects for an economic recovery. These pressures are compounded by the risk of a prolonged period of restrictive monetary conditions, which could further constrain investment and domestic demand. European equity indices could therefore continue to rise without a broad-based improvement in the underlying economy, supported solely by a limited number of sectors capable of preserving their margins or benefiting from international economic imbalances.
Our assessment remains cautious despite the stronger performance of European equity markets. Their sector diversification helps them withstand a correction in US technology stocks, but does not shield them from a broader slowdown in the global economy. Unlike the United States, where investment in artificial intelligence is a major driver of economic activity, Europe remains more dependent on international demand and a still-fragile industrial recovery. Adding to these uncertainties is the renewed deterioration in French government bonds (OATs), prompting us to monitor French banking stocks more closely given the risk of sovereign market pressures spilling over into the financial sector, even though funding conditions have yet to show signs of significant stress. More broadly, a sustained rise in European equity indices would require earnings growth to broaden beyond the sectors currently benefiting, rather than relying primarily on capital reallocations. At this stage, we believe European markets are benefiting more from weaknesses in the US market than from expectations of a genuine economic recovery.

Macron, a Cancer for the Republic

This week, we discovered what looks like another brilliant idea from the Macronist political genius. After methodically contributing to the rise of the far right, Emmanuel Macron believes he has found a champion to dilute the left-wing vote, Teddy Riner! The judoka has announced his candidacy for the presidential election, and now the President of the Republic is publicly welcoming this initiative. As luck would have it, several figures from the Macronist circle can be found among the athlete's entourage, François Braun, former Minister of Health, and Philippe Véran, an early supporter of Emmanuel Macron.
Are Macronist strategists hoping to divert part of the working-class electorate, particularly Jean-Luc Mélenchon's voters, toward a candidacy likely to further split the left-wing vote? That is what their latest brilliant idea amounts to, taking an Olympic champion, banking on his popularity, and then hoping to turn a gold medal into an electoral machine. Skin color could even become, in the most cynical calculations, an argument designed to appeal to working-class neighborhoods. Someone had to think of it!
Unfortunately for the sorcerer's apprentices, the first opinion polls have dampened the enthusiasm. Teddy Riner attracts only 4% of voting intentions. The irony is that this candidacy could also weaken candidates from the center and the Socialist Party. After spending years explaining to the French that they understood nothing about essential reforms, the Macronists may discover that they understand no more about how voters behave, or that there is a desire to favor a vote for Le Pen. Yet another masterpiece of political strategy!
But imagine these brilliant strategists claiming to resolve international crises, arbitrate conflicts between major powers, and lecture the entire planet on democracy, with an Emmanuel Macron who continues to dream of himself as a great universal mediator. We could laugh about it. We could even turn it into an excellent political comedy. Unfortunately, what is currently happening in France is no longer much of a comedy.

For while the Élysée contemplates its electoral maneuvers, abuses about policing methods continue to pile up. In Pontoise, teenagers who claim to have been slapped and insulted by police officers in the holding area of the judicial court. According to Le Canard enchaîné, one of these young people reports that an officer allegedly told him, "Here we can kill you, there are no cameras." A judicial investigation has been opened. In Brest, police officers obtained, under a judicial requisition, the school photo directories of three high schools at the Kerichen educational complex, potentially covering some 4,500 pupils and students. Thousands of faces, names, and surnames, including those of numerous minors, collected. The public prosecutor's office denies any systematic profiling and defends the legality of the procedure. But the French Lawyers' Union warns of the risk of disproportionate collection of personal data. Why should thousands of teenagers potentially be caught up in investigations targeting a handful of individuals? It is certainly curious to see a government that constantly invokes the protection of freedoms treating these questions as secondary.
Even more seriously, the investigation published by Disclose on November 3 gathered testimonies from protesters accusing police officers of sexual violence, among fifteen people identified by the outlet, including six minors. Unwanted touching, humiliation, searches denounced as abusive, acts of a sexual nature, the accounts are particularly disturbing. These accusations must, of course, be subject to thorough and impartial investigations. But how many more testimonies will it take before political leaders understand that the response cannot be limited to a few ministerial statements?
Meanwhile, footage recorded by protesters, now ubiquitous thanks to mobile phones, exposes new cases of police misconduct and new violations of the law and the Constitution every week. This is what bothers certain officials the most, the possibility that citizens can document for themselves the behavior of those who are supposed to protect them. Violence is no longer necessarily concealed behind an official administrative account of events. It can be filmed, circulated, analyzed, and compared with witness testimonies. The official narrative is no longer enough to impose a single version of the truth.
Journalists are beginning to grasp the scale of the problem. Reporters Without Borders has recorded cases of obstruction of journalists' work during social protests. Seven journalists have filed a collective complaint, supported by several trade unions. Laurent Nuñez received them and promised improvements. Admirable! It took journalists themselves beginning to suffer blows for the Ministry of the Interior to discover the urgent need to recall the basic rules of policing in a republic.

This should raise some serious questions in a French media landscape where the concentration of ownership, the relationships between major economic groups and political power, and public subsidies to the press deserve a far more serious democratic debate. How can we avoid questioning the conditions of their genuine independence when shareholders simultaneously hold major economic interests, influential media outlets, and privileged relationships with those in power? The issue is not to declare that all journalists are accomplices. It is to understand why we so often have to wait for investigations by independent media outlets before scandals emerge that institutional authorities would have every reason to examine publicly.

A collective of lawyers representing injured individuals has announced its intention to bring a case against Laurent Nuñez before the Court of Justice of the Republic. Among the injuries reported are mutilations and irreversible damage to physical integrity. Young people have lost an eye, others a hand, while still others have suffered serious fractures. And when a member of the police seems to regard these consequences as a mere "risk," we can measure the moral abyss separating such indifference from the severity of the suffering inflicted. A severed hand is not an administrative incident. A lost eye does not grow back after a press conference. Why are Emmanuel Macron and Sébastien Lecornu not being held accountable when they are violating the law and the Constitution?

Finally, there remains this curious convergence between the disintegration of Macronism and the gradual normalization of the far right. Marine Le Pen recently met several executives from major industrial groups, including Dassault, Renault, TotalEnergies, and Safran, at a dinner organized by France Industrie on the premises of the UIMM. Meeting candidates is, of course, entirely legitimate for business representatives, and France Industrie has also held discussions with Jean-Luc Mélenchon. But the presence of the far right at the table of major corporate leaders illustrates just how much political and economic boundaries are being reshaped as 2027 approaches, with Macron as a useful puppet to fuel chaos and finish turning France into a wasteland.
So, is Emmanuel Macron taking part in a strategy from which the National Rally could emerge as the main beneficiary? The question deserves to be asked. On the other hand, imagining the existence of a secret pact designed to protect the president from possible financial investigations where he is suspected of corruption, at this stage, be an unsubstantiated hypothesis. This observation in no way removes the need to demand that sensitive cases, allegations of suspected corruption, and relationships between political power and private interests be examined by a genuinely independent judiciary, regardless of the personalities involved.
France, however, lacks neither laws, nor judges, nor constitutional principles. What it lacks is one fundamental political requirement, that those who exercise power should genuinely be held accountable for the way in which that power is exercised.
Macron, who so enjoys lecturing the entire world on democracy, refuses to allow children to demonstrate without risking mutilation, journalists to work without being beaten, and himself to stop treating checks and balances as a personal inconvenience. And since the idea seems excessive to him, let us remind him of this message from America, "LAWYER UP!"

And as for Europe, Sister Anne, what do you see? Still nothing!

Flag USUS 10-year government at 5.141

10-year T-Note US Government

Buyer PressureSeller Pressure

Fundamental trend : Bullish

The predominant buying pressure continues to increase at a slowing pace, the selling pressure declines at a sustained rate.

For this week, the US 10-year Treasury yield is expected to test the 5.177 / 5.190 resistance zone before finding a ceiling below the 5.254 / 5.263 level.

Its downward movements should be limited to the 5.022 / 5.002 support zone.

Volatility HV * 21 D. 252 D. LTV
Average range * Daily 0.088 Weekly 0.217
Max. weekly range * 4.924 5.358

* Anticipated

Flag GermanGerman 10-year government at 3.378

10-year Bund German Future and yield

Buyer PressureSeller Pressure

Fundamental trend : Bullish

The buying pressure is increasing at an accelerating pace, the predominant selling pressure is declining at a steady rate.

For this week, the German 10-year bond yield is expected to test the 3.392 / 3.409 resistance zone before finding a ceiling below the 3.442 / 3.457 level.

Its downward movements should be limited to the 3.301 / 3.287 support zone.

Volatility HV * 21 D. 252 D. LTV
Average range * Daily 0.052 Weekly 0.137
Max. weekly range * 3.241 3.515

* Anticipated

FrenchFrench 10-year government at 4.921

Volatility HV * 21 D. 252 D. LTV
Average range * Daily 0.072 Weekly 0.237
Max. weekly range * 4.684 5.158

* Anticipated

Italian flagItalian 10-year government at 4.419

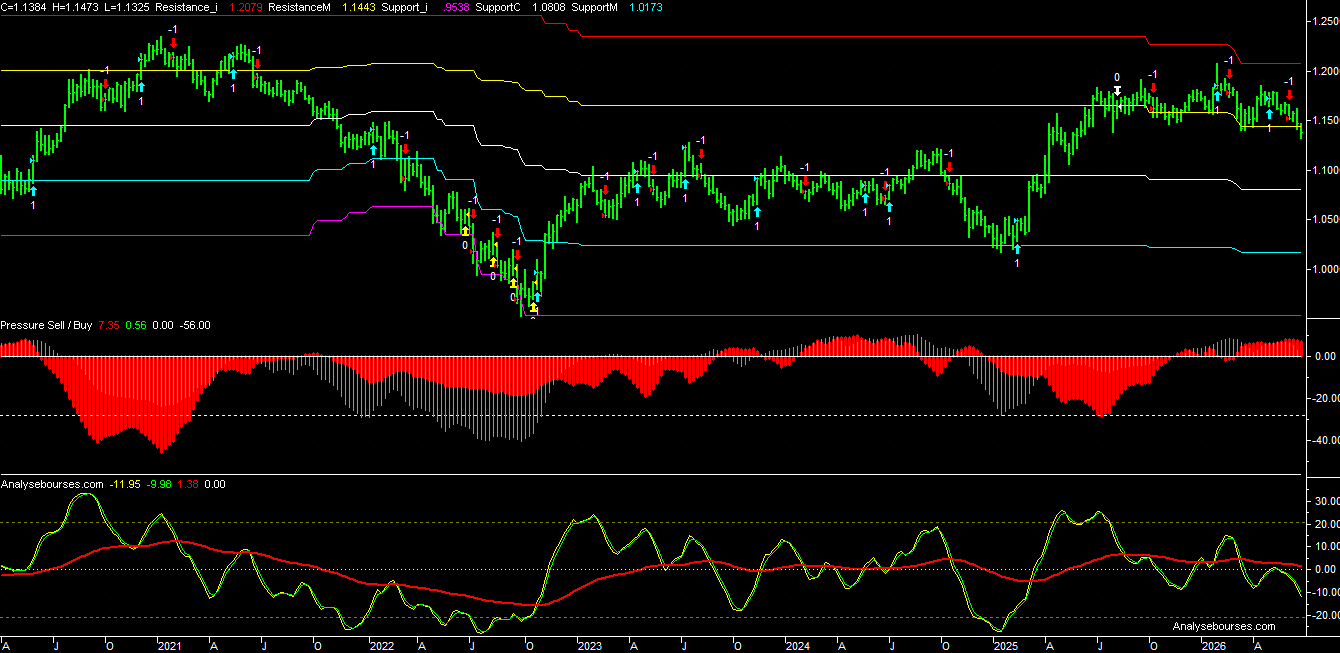
Flag EuropeEURUSD at 1.1023

EURUSD quotation and volatility

Buyer PressureSeller Pressure

Fundamental trend : Bearish

The buying pressure decreases by accelerating its speed, the predominant selling pressure increases by decreasing its speed.

For this week, the single currency should test its 1.0993 / 1.0949 support level for possible support on the 1.0902 / 1.0880 area.

Its bullish movements should be limited to the 1.1128 / 1.1163 resistance zone.

Volatility HV * 21 D. 252 D. LTV
Average range * Daily 0.0061 Weekly 0.0183
Max. weekly range 1.0840 1.1206

* Anticipated

Flag USSP500 at 7561

SP500 Index quotation and volatility

Buyer PressureSeller Pressure

Fundamental trend : Consolidation

The buying pressure is declining at a steady pace, the prevailing selling pressure remains stagnant.

For this week, the index is expected to test the 7473 / 7462 support zone before finding a bottom in the 7380 / 7320 area.

The upward movements should be limited to the 7683 / 7692 resistance zone.

Volatility HV * 21 D. 252 D. LTV
Average range Daily 92 Pts Weekly 183 Pts
Max. weekly range 7378 7744

* Anticipated

VIX SPOT 19.30 Close 2026/11/13
SPX ATM IV November 15.635 % Δ -5.900 pt - (CALL 15.687 % | PUT 15.583 %)
SPX ATM IV December 15.038 % Δ -4.814 pt - (CALL 15.037 % | PUT 15.040 %)
SPX ATM IV January 15.168 % Δ -3.964 pt - (CALL 15.173 % | PUT 15.163 %)

November Expiry The November expiry records a sharp decline in the price of volatility. ATM implied volatility falls from 21.53% to 15.63%, after reaching a low of 13.72% on Wednesday. This decline reflects a genuine reduction in the volatility premium, beyond the mechanical effect of the index's movement. However, the easing remains uneven, with OTM puts close to the current index level losing substantial value, while more distant downside protections retain a relatively high valuation.
At 5% below the SP500, implied volatility declines by 5.69 points, compared with 2.66 points at 10%, while increasing by 3.55 points at 20%. The slope of the smile flattens near the ATM level but steepens in the downside wings, increasing its convexity. OTM calls display a similar pattern, with volatility easing near the current index level but rising at more distant strikes. These movements should nevertheless be viewed with caution. As expiration approaches, premiums on far OTM options become very small and their implied volatilities particularly sensitive to quoted prices, without necessarily indicating a significant increase in their economic cost.

December Expiry The December expiry follows November's easing, but with a more uniform adjustment across the smile. ATM implied volatility declines from 19.85% to 15.04%, while OTM puts lose value across all distances from the current index level, including the most distant downside protections. At 10% below the SP500, the decline reaches 4.57 points, compared with 2.66 points for November. This confirms a genuine reduction in the price of medium-term risk, beyond the mechanical effect of the index's rebound.
The downside slope of the smile flattens moderately, while its convexity increases, reflecting a broad decline in volatility without eliminating the premium attached to extreme downside protection. OTM calls close to the current index level also record lower volatility, while the distant upside wings prove more resilient, mainly due to the index's movement. Unlike November, the changes remain more uniform and show no significant independent repricing at the extremes of the smile.
Constant-delta measures confirm a less pronounced decline than in November. The 10-delta put falls from 32.80% to 24.78%, but now exceeds its November counterpart. The volatility gap between 5-delta puts and calls narrows from 26.23 to 18.79 points, compared with 12.12 points for November. December therefore retains a more persistent premium on downside scenarios, despite the broad normalization of volatility. The modest rebound observed toward the end of the week also highlights this expiry's sensitivity to renewed tensions, without reproducing the magnitude of November's fluctuations.

January Expiry The January expiry continues the normalization of volatility pricing, although less intensely than the preceding expiries. ATM implied volatility declines from 19.13% to 15.17%, now slightly above December. OTM puts ease across the entire smile, without the repricing of extreme downside protection seen in November. The downside slope flattens slightly, while convexity increases moderately. OTM calls close to the current index level also participate in this easing, confirming a genuine reduction in the price of volatility beyond the mechanical effect of the SP500 rebound.
Constant-delta measures nevertheless reveal greater persistence in the downside premium. The 5-delta put falls from 38.53% to 31.21%, while the 10-delta put declines from 31.46% to 25.28%. The volatility gap between 5-delta puts and calls narrows from 25.16 to 19.70 points, but now exceeds that of the two preceding expiries. This reversal in the maturity hierarchy reflects a slower decline in the price of distant downside protection, rather than a renewed repricing of bearish scenarios. January therefore retains the highest relative valuation of extreme downside risks at comparable deltas, despite a broad decline in volatility. Volatility also falls on more distant expiries, but protection against a decline in the SP500 remains relatively more expensive than in November. This resilience contrasts with November's much faster easing and confirms that the reduction in immediate risk is not accompanied by an equivalent decline in the price of medium-term correction scenarios.

Volatility Premium The VIX futures term structure records a sharp reversal compared with the previous week. The VIX cash index falls from 25.64 to 19.30, while the November future declines from 23.70 to 19.60. The December and January expiries fall more moderately, to 19.75 and 20.35 respectively. Backwardation between November and December disappears, with the spread moving from -1.60 to +0.15 points. The return to contango confirms a rapid normalization of immediate risk, while later expiries retain a more resilient premium. This easing nevertheless stalled toward the end of the week, with the VIX cash index rebounding from Wednesday's low of 17.49 and contango narrowing.
This development is consistent with the decline in SPX implied volatilities, particularly pronounced in November, while December and January retain higher valuations for downside protection. VIX options also confirm the easing, with ATM volatility falling from approximately 157% to 111% in November, compared with 106% to 89% in December and 85% to 77% in January. Uncertainty surrounding future VIX fluctuations declines substantially, without disappearing on the nearest expiries. Overall, this reflects a significant reduction in the immediate risk premium. The return to contango marks the disappearance of the exceptional tensions observed previously, but the rebound in volatility toward the end of the week shows that this easing remains fragile.

Outlook Implied price ranges have narrowed significantly. November now prices in a one-standard-deviation move of approximately 164 points around 7562, implying an indicative range between 7398 and 7725. December implies a 352-point move, between 7210 and 7914, while January reaches 477 points, between 7085 and 8038. The support levels at 7016 and 6920 now lie beyond these ranges, illustrating the reduction in expected market movements compared with the previous week.
The current configuration reflects a significant normalization in the price of volatility, although the decline remains less pronounced for deferred downside protection. The renewed tensions toward the end of the week nevertheless warrant close attention to market reactions around 7516 and 7482, as well as the SP500's ability to break sustainably above 7620. The evolution of OTM puts and the VIX futures term structure will help distinguish a temporary consolidation from a more sustained recovery or a renewed increase in the price of downside risk.

The regular purchase of small OTM puts only harms the seller.